Author: Tomas Hula

  • Outline Raises $3M to Build an AI Intelligence Layer for Corporate Finance

    Outline Raises $3M to Build an AI Intelligence Layer for Corporate Finance

    Paris-based financial technology startup Outline has raised $3 million in seed funding to build out its AI-driven financial planning platform and expand across Europe and the United States.

    The round was led by Founders Future, with participation from 100in, Newschool and a syndicate of fintech business angels. Outline will use the capital to expand its engineering and machine learning teams, accelerate product development and increase commercial deployment with corporate finance teams.


    Moving Beyond the Financial Model

    Outline is building an AI-powered workspace designed to continuously model and simulate a company’s financial position. Rather than relying on finance teams to manually consolidate data and update forecasts, the platform connects to the systems where that information already exists.

    These include accounting ledgers, billing software, payroll networks, sales pipelines and spreadsheets. Outline then uses specialized AI agents to analyse the company’s historical transaction data, generate a financial model and continuously compare its forecasts with actual results from previous months.

    The objective is to turn financial planning from a periodic exercise into an ongoing process. Instead of producing a forecast, reviewing it and updating it weeks or months later, finance teams can work with a model that continuously tests its own assumptions against what is actually happening in the business.


    AI as a Layer Across Finance Data

    The approach is particularly relevant as companies accumulate financial information across an increasingly fragmented technology stack. Accounting, payroll, sales and billing systems each contain part of the picture, while spreadsheets often remain the layer where finance teams bring everything together.

    Outline is attempting to sit above that infrastructure rather than replace it. By connecting existing data sources, the platform can create a unified view of the business without requiring companies to migrate their underlying systems.

    The AI agents then become an intelligence layer on top of that data, supporting financial modelling and automated simulations. For finance teams, the potential value is not simply faster spreadsheet work, but the ability to test different scenarios continuously as new information enters the business.


    Early Enterprise Adoption

    Outline has already been adopted by several high-growth companies, including Zelty, Harmattan AI, Shares and HarfangLab.

    That early customer base gives the company an opportunity to develop its platform around businesses where financial planning becomes increasingly complex as they scale. The challenge now is to turn that early adoption into a repeatable commercial model across multiple markets.

    The new funding will support that expansion while giving Outline additional resources to develop the engineering and machine learning capabilities behind the platform.


    The Bigger Shift in Corporate Finance

    The broader opportunity for Outline is the changing role of AI inside finance departments. Much of the first wave of financial AI focused on automating individual tasks such as data extraction, reporting or reconciliation.

    Outline is targeting a higher-level layer: understanding how the different financial activities of a company interact and continuously simulating what could happen next.

    If the platform can reliably connect operational data with financial outcomes, financial planning becomes less about maintaining a static model and more about continuously understanding the business. That could make scenario planning more accessible to companies that do not have large financial planning and analysis teams.


    Key takeaways for fintech startups

    • Build on existing infrastructure: Outline connects to the systems companies already use instead of asking them to replace their financial stack.

    • AI can move upstream: The opportunity is expanding from automating finance tasks to supporting higher-level planning and decision-making.

    • Continuous forecasting can change workflows: Financial models become more useful when they are constantly tested against actual business performance.

    • Complexity creates demand: As companies scale across multiple systems, the value of an intelligence layer that connects financial data increases.

    • Early enterprise adoption matters: Initial customers can provide the data, workflows and validation needed to turn an ambitious AI product into a repeatable enterprise offering.

    Outline is betting that the next generation of corporate finance software will not simply report what happened. It will continuously model what is happening and help finance teams understand what could happen next. If you’re building an AI-enabled fintech and looking to turn the technology into a scalable business, Contact us.
  • Sav Raises $3.5M to Build an AI-Powered Money Management Platform Across the GCC

    Sav Raises $3.5M to Build an AI-Powered Money Management Platform Across the GCC

    UAE-based consumer fintech Sav has raised $3.5 million in a Pre-Series A round led by Abu Dhabi-based Phoenix Venture Partners, with participation from co-investors from the Phoenix Venture Partners Innovation Fund. The funding will support Sav’s expansion into Saudi Arabia while accelerating product development, AI infrastructure and user acquisition across the GCC.

    Founded by Purvi Munot and Mithil Ajmera, Sav is building a financial platform designed to bring savings, investments, gold, payments and commerce into a single ecosystem. The company operates under a DFSA Category 4 license in the UAE and has previously raised approximately $2.5 million.


    From Financial Products to Financial Management

    Sav is positioning itself around a broader consumer proposition than a single financial product. Its platform aggregates users’ financial accounts in one place and uses its proprietary AI infrastructure, SavCore, to automate parts of saving, investing, credit management and wealth building.

    That approach reflects a broader shift in consumer fintech. The first generation of digital finance focused heavily on making individual products easier to access, from payments to BNPL. Sav is betting that the next opportunity is helping consumers manage multiple financial products through one intelligent layer.

    The distinction is important. Instead of asking consumers to choose another financial product, Sav wants to become the platform through which they understand and manage the products they already have.


    Why Saudi Arabia Matters

    The new funding will primarily support Sav’s go-to-market expansion into Saudi Arabia, which the company identifies as a key strategic market alongside its broader GCC expansion.

    For Sav, geographic expansion is closely connected to its product proposition. The company is targeting consumers whose financial lives can span multiple accounts, products and potentially countries, creating a need for a platform that can provide a more complete view of their finances.

    Its model is also supported by diversified revenue streams, including interchange income, wealth management fees, commerce commissions and subscriptions. Sav says it has already demonstrated strong early growth alongside efficient customer acquisition economics.


    The GCC’s Next Fintech Layer

    Phoenix Venture Partners’ investment reflects a specific view of where regional fintech is heading. The firm argues that the next major opportunity will not necessarily come from building another payment rail, but from creating financial products and experiences on top of the infrastructure that already exists.

    That includes lending, insurance, wealth management and embedded finance. Sav fits into this thesis by putting AI at the center of the consumer experience rather than treating it as an additional feature.

    The company’s ambition is therefore considerably broader than building another savings or investment app. It is attempting to create an intelligent financial layer that can understand a consumer’s wider financial position and automate decisions across different products.


    From Consumption to Wealth Building

    The comparison with BNPL is particularly revealing. BNPL helped change how consumers access spending by making credit available at the point of purchase. Sav is betting on the opposite side of the financial relationship: helping consumers save, invest and build wealth.

    That creates a potentially more durable relationship with users. Spending products can generate frequent transactions, but a platform that becomes part of someone’s savings, investments and broader financial management can become embedded in their long-term financial life.

    The immediate test is whether Sav can translate that proposition into Saudi Arabia and then scale it across the GCC. The $3.5 million round gives the company capital to expand geographically while continuing to build the AI infrastructure underneath the platform.


    Key takeaways for fintech startups

    • Move beyond individual products: The next layer of fintech may be about managing multiple financial relationships rather than offering another standalone product.

    • AI needs a real job: SavCore is positioned as infrastructure for automating financial decisions, not simply an AI feature added to the user interface.

    • Expansion needs a strong local market thesis: Saudi Arabia is a strategic growth market for Sav, making regional expansion part of the company’s core strategy rather than an afterthought.

    • Diversified revenue can strengthen the model: Interchange, wealth management, commerce and subscriptions give Sav multiple potential monetization paths.

    • Follow the next consumer shift: BNPL helped finance consumption. Sav is betting that AI-led money management can help consumers build wealth.

    Sav’s next phase will test whether consumers are ready to move from using fintechs for individual transactions to relying on one platform to manage their broader financial lives. If you’re building a fintech platform and need help shaping your growth strategy, Contact us.

  • Triver Raises ÂŁ8M to Turn Cashflow Streaming Into Embedded SME Finance

    Triver Raises ÂŁ8M to Turn Cashflow Streaming Into Embedded SME Finance

    UK fintech Triver has raised an additional £8 million in a Series B equity round led by Calderwood Capital, with support from existing investors. The round brings the company’s total venture capital investment to £30 million as it looks to scale its Cashflow Streaming proposition for small and medium-sized businesses.

    Founded in London in 2023, Triver uses bank account data, accounting data and AI to assess SME borrowing risk and advance cash against outstanding invoices. The company says businesses can receive a new facility of up to ÂŁ700,000 within 10 minutes of starting an application, while individual invoices can typically be funded in less than five minutes.


    The Real Product Is Speed

    Traditional SME finance often requires businesses to wait for applications, underwriting and manual checks before accessing working capital. Triver is building around a different assumption: if a fintech can analyse a company’s financial data in real time, funding decisions can happen when the business actually needs the money.

    Its integrations with Sage, Xero and QuickBooks allow Triver to connect directly to the accounting systems where invoices already exist. Fees start at 1.8% for a 30-day invoice, giving businesses a way to turn outstanding receivables into cash without waiting for customers to pay.

    The proposition appears to be resonating with its target market. Triver now serves 2,400 clients and has financed more than 40,000 invoices worth ÂŁ400 million since launch. More than 90% of its monthly revenue comes from repeat usage, while its Net Promoter Score stands at 92.


    From Fintech Product to Embedded Infrastructure

    The next phase of Triver’s strategy is particularly interesting. The company plans to use the new capital not only to improve its own product, but also to build integrations with brands that want to offer funding directly to their SME customers.

    Triver is already working with Tide Bank to make Cashflow Streaming available within its environment, with additional embedded finance partnerships in development. This creates a second distribution model for the company. Instead of acquiring every SME directly, Triver can become the financing infrastructure behind platforms that already serve them.

    That shift could materially expand its addressable market. Accounting platforms, banks and other SME-focused software providers already have the customer relationships and financial data. Triver can provide the underwriting and funding layer on top.


    Data Is Changing SME Underwriting

    Triver’s model also reflects a broader evolution in business lending. Access to bank transaction data and accounting information gives lenders a much more current picture of an SME’s financial position than traditional application-based underwriting.

    For Triver, AI is what turns that data into an automated decisioning process. The company’s proposition is built around continuously assessing the business rather than treating financing as a one-off application.

    The model is led by Jerome Le Luel, who previously served as Chief Risk Officer at Funding Circle and Global Head of Risk Analytics at Barclays. That background is particularly relevant for a company whose core challenge is balancing faster access to capital with responsible risk assessment.


    Key takeaways for fintech startups

    • Solve the timing problem: Triver is addressing a fundamental SME pain point by making capital available when invoices are created rather than when customers eventually pay.

    • Turn data into infrastructure: Bank and accounting data become significantly more valuable when they can support automated financial decisions.

    • Build distribution into the model: Embedded partnerships can allow fintechs to scale through existing customer relationships rather than relying entirely on direct acquisition.

    • Repeat usage matters: More than 90% of Triver’s monthly revenue coming from repeat customers suggests the product is becoming part of customers’ ongoing financial workflows.

    • Speed only works with risk controls: Faster underwriting needs strong data and risk expertise underneath it, particularly in SME finance.

    Triver is now moving from proving that businesses want faster invoice funding to proving that Cashflow Streaming can become a broader infrastructure layer for SME finance. If you’re building a fintech product and looking to turn it into scalable financial infrastructure, Contact us.

  • Plenti Raises $3M to Take Its Multicurrency Model Across Latin America

    Plenti Raises $3M to Take Its Multicurrency Model Across Latin America

    Colombian fintech Plenti has raised $3 million in a seed round led by Tether, the issuer of the USDT stablecoin, with participation from Verda Ventures. The funding comes as Plenti prepares to take its multicurrency and investment platform beyond Colombia into Peru and Bolivia.

    The company already has more than 150,000 active users and processes more than $3.1 billion in annual transaction volume across its B2B and B2C businesses. That makes the round less about proving demand in its home market and more about putting capital behind an expansion that is already underway.


    Scaling a Multicurrency Platform

    Plenti operates across international payments, multicurrency accounts and retail investment products. Users can hold and move money internationally, earn up to 8% EA on balances, and invest fractionally in U.S.-listed stocks, ETFs and crypto assets from as little as $6.

    The model puts Plenti in competition with a growing group of Latin American fintechs building alternatives to traditional banking around digital dollars and easier access to international financial markets. ARQ, formerly DolarApp, Littio and Bitso are among the platforms targeting similar demand.

    For Plenti, the next test is whether the model can travel. Peru and Bolivia will give the company two new markets in which currency volatility, access to foreign currency and demand for international financial products can create similar opportunities.


    Why Tether Is Investing

    Tether’s participation adds another dimension to the round. USDT has become a major part of the digital-dollar infrastructure used across emerging markets, particularly where local currencies are subject to significant volatility.

    Tether reported approximately $184.6 billion in USDT circulation at the end of the second quarter of 2026, giving it more than 60% of the global stablecoin market. An investment in a fintech such as Plenti therefore creates a direct connection between a major stablecoin issuer and a platform using the broader demand for digital dollars as part of its financial offering.

    For Plenti, the partnership is also relevant to the infrastructure behind its expansion. Co-founder and CTO MartĂ­n PelĂĄez says the new capital will help strengthen liquidity and security as the company enters additional Latin American markets.


    Capital to Accelerate, Not Validate

    Plenti’s funding strategy is notable because the company is raising after establishing meaningful transaction volume in Colombia rather than using the seed round to prove that its business works.

    The company says it did not need the capital to grow its Colombian operation. Instead, the $3 million is intended to accelerate the next stage and replicate the model in new markets.

    That distinction matters in fintech. Expanding a financial platform across borders requires more than customer acquisition. Liquidity, compliance, security and local infrastructure all have to work market by market. Plenti is using the new capital to tackle those requirements while it still has momentum in its core business.


    Key takeaways for fintech startups

    • Raise for acceleration: Plenti is using new capital to expand an operating business rather than fund the initial proof of demand.

    • Expansion requires infrastructure: Cross-border fintech growth depends on liquidity, security and local market capabilities as much as customer acquisition.

    • Stablecoins are becoming financial infrastructure: Tether’s investment reflects the growing role of digital dollars in Latin American financial products.

    • A focused product can travel: Multicurrency accounts and international financial services can address similar customer needs across multiple markets, but each expansion still requires local execution.

    Plenti now has to prove that the model that works in Colombia can scale across very different Latin American markets. The $3 million round gives it the capital and a strategic stablecoin partner to make that next move. f you are working on a similar growth challenge, Contact us⁠.

  • FĂ©lix Pago Raises $200M to Turn WhatsApp Remittances Into a Digital Bank

    Félix Pago Raises $200M to Turn WhatsApp Remittances Into a Digital Bank

    Miami-based fintech Félix Pago has raised $200 million in new financing as it moves beyond remittances and toward becoming a broader financial platform for Hispanic immigrants in the United States.

    The round combines $87 million in equity led by Andreessen Horowitz with $113 million in debt financing from General Catalyst. QED Investors also participated in the equity round. The funding gives Félix Pago significant room to expand its geographic footprint while building new AI-powered financial products around an existing customer base.


    From WhatsApp Remittances to Financial Services

    Félix Pago launched in 2022 with a simple proposition: make sending money abroad feel more like having a conversation than using a traditional financial service. Customers interact with an AI chatbot through WhatsApp, while the underlying infrastructure handles the conversion and delivery of funds.

    The company has now processed more than $8 billion in remittances and served more than six million people across 11 Latin American countries. Mexico remains its largest market, while Colombia is becoming an important growth market.

    The technology behind the experience is equally important. Félix Pago uses USDC stablecoins through Circle and Bridge to move value between the U.S. and local markets, with recipients ultimately receiving local currency. For customers, however, the complexity of the underlying infrastructure largely disappears behind a familiar messaging interface.


    The Bigger Opportunity Is the Customer Relationship

    The most important part of this funding may be what Félix Pago does after the transfer is complete.

    The company plans to use the new equity capital to expand into additional markets and develop AI-powered products for Hispanic immigrants. Reported plans include short-term “Send Now Pay Later” loans, high-yield savings accounts and an AI financial assistant.

    That changes the economics of the business. Remittances can provide a high-frequency entry point into a financial relationship, but the larger opportunity is to build additional products around the same customer. If Félix Pago can turn a transaction used to send money home into an ongoing relationship covering savings, credit and financial guidance, it moves from being a remittance provider toward becoming a digital banking platform.


    AI Is the Interface, Not the Product

    FĂ©lix Pago’s approach also highlights an important shift in how financial services can be delivered. The chatbot is not simply an AI feature added to a traditional banking interface. WhatsApp is effectively becoming the interface through which customers access financial services.

    That matters particularly for underserved customers who may find conventional banking applications, forms and processes unfamiliar or difficult to navigate. The product removes much of that friction while keeping the underlying financial infrastructure largely invisible.

    For Félix Pago, the challenge now is to extend that simplicity beyond remittances without making the product more complicated as more financial services are added.


    A Large and Growing Market

    The opportunity behind the strategy is substantial. The FDIC reported that 9.5% of Hispanic households in the U.S. were unbanked in 2023, compared with 1.9% of white households. At the same time, remittances to Latin America and the Caribbean reached a record $173.7 billion in 2025.

    Félix Pago has already established a significant position within that ecosystem. Its previous funding included a $75 million Series B in April 2025, following a $15.5 million Series A and a $2.8 million seed round.

    The new $200 million round therefore represents more than another step in the company’s fundraising history. It gives FĂ©lix Pago the capital to test whether a product built around one of the most frequent financial needs of immigrant households can expand into a much broader banking relationship.


    Key takeaways for fintech startups

    The Félix Pago story offers several lessons for fintechs looking to build beyond a single financial product:

    • Start with a frequent financial need: Remittances gave FĂ©lix Pago a recurring use case and a large customer base from which to expand.

    • Make complexity invisible: Stablecoins and financial infrastructure can sit behind a familiar interface rather than becoming something customers need to understand.

    • Think beyond the first transaction: The biggest opportunity may come from expanding an existing customer relationship into savings, credit and other services.

    • AI can become the interface: For some customer segments, conversational financial services may remove more friction than simply adding AI features to an existing banking app.

    • Design around underserved customers: Building specifically for a customer group overlooked by traditional providers can create both a strong product proposition and a large market opportunity.

    For fintechs looking to turn a focused product into a broader financial platform, Félix Pago shows how customer experience, infrastructure and AI can come together to create a much bigger opportunity. If you are working on a similar growth challenge, Contact us.

  • Bull Raises $3.9M to Put AI at the Core of Credit Infrastructure

    Bull Raises $3.9M to Put AI at the Core of Credit Infrastructure

    Brazilian fintech Bull has raised R$20 million, roughly $3.9 million, in a seed round led by Maya and Caravela, with participation from Canary.

    What makes the round interesting is not just the funding itself. Bull is raising before it needs the money, using fresh capital to accelerate AI, data infrastructure and cybersecurity rather than waiting for growth to create a cash bottleneck.


    Raising Before the Cash Runs Out

    The new round comes less than a year after Bull raised R$10 million in pre-seed funding from Canary in October 2025. According to COO JosĂ© Pires Neto, the company still has much of that capital available, but doesn’t want to wait until its cash position becomes a constraint before raising again.

    For an early-stage fintech, that is a deliberate approach to capital management. Instead of treating fundraising as a response to financial pressure, Bull is using it as a tool to accelerate a growth plan that is already underway.


    Building the Infrastructure for Credit

    Bull operates a credit-as-a-service platform that allows businesses to launch and manage their own credit products. The company started with private payroll-deducted credit, but its infrastructure was designed to support multiple products as it scales.

    Bull now serves more than 20 medium and large businesses and is targeting R$1 billion in credit operations by the end of 2026. The next challenge is therefore less about proving the initial product and more about building the technology, data and risk infrastructure required to support a broader credit business.


    Putting AI Into the Core

    A significant portion of the new funding will go toward artificial intelligence, data infrastructure and cybersecurity. Bull plans to integrate AI directly into the core of its platform while adding a cybersecurity intelligence layer.

    For a credit infrastructure provider, that can affect much more than internal efficiency. Better data and AI can improve credit decisioning, risk assessment, fraud detection and portfolio management, allowing the platform to become more intelligent as it processes more credit.


    Experience Behind the Expansion

    Bull was founded in 2025 by Juliana Freitas and José Pires Neto, who previously led FortBrasil. That business grew to more than 2 million customers and originated R$20 billion in credit before being acquired by DM in 2023.

    That experience gives Bull a different starting point from many young fintechs. The founders have already operated at significant scale in credit and are now applying that experience to a platform designed to let other businesses launch and operate credit products.


    Key takeaways for fintech startups

    • Raise before the bottleneck: Bull is using capital to accelerate growth instead of waiting until cash becomes a constraint.

    • Build beyond the first product: Credit infrastructure becomes more valuable when the same technology can support multiple products and use cases.

    • Make AI operational: AI can influence risk, security and decisioning when it is embedded into the underlying credit infrastructure.

    • Use experience as an advantage: Founders with deep domain experience can move faster when building the infrastructure behind a complex financial product.

    Bull’s strategy is straightforward: build the infrastructure, make it intelligent, and scale before capital becomes the constraint.

    If you’re building the next generation of fintech infrastructure and need help turning that vision into a growth strategy, Contact usâ ïżŒ.

  • Corgi Raises $106M at $2.6B Valuation Just Three Weeks After Its $160M Round

    Corgi Raises $106M at $2.6B Valuation Just Three Weeks After Its $160M Round

    Corgi has raised another $106 million, taking its valuation to $2.6 billion just three weeks after announcing a $160 million round at $1.3 billion.

    That is more than a funding milestone. It is a sign of how quickly investors are betting on the modernization of commercial insurance infrastructure.


    From $1.3B to $2.6B in Three Weeks

    The Series B1 was led by TCV, with participation from Prime Capital, Zone 2 Ventures, Oliver Jung, Leblon Capital, Kindred Ventures and other investors.

    The timing is what makes the raise particularly notable.

    On May 6, Corgi announced $160 million at a $1.3 billion valuation. Just 21 days later, the company has effectively doubled its valuation through a new $106 million financing.

    Combined with its previously announced $108 million Series A, Corgi has now raised $378 million.

    And according to founder and CEO Nico Laqua, the company was already profitable last month.


    Why Investors Are Moving So Quickly

    Commercial insurance remains heavily dependent on manual processes, fragmented systems and legacy infrastructure.

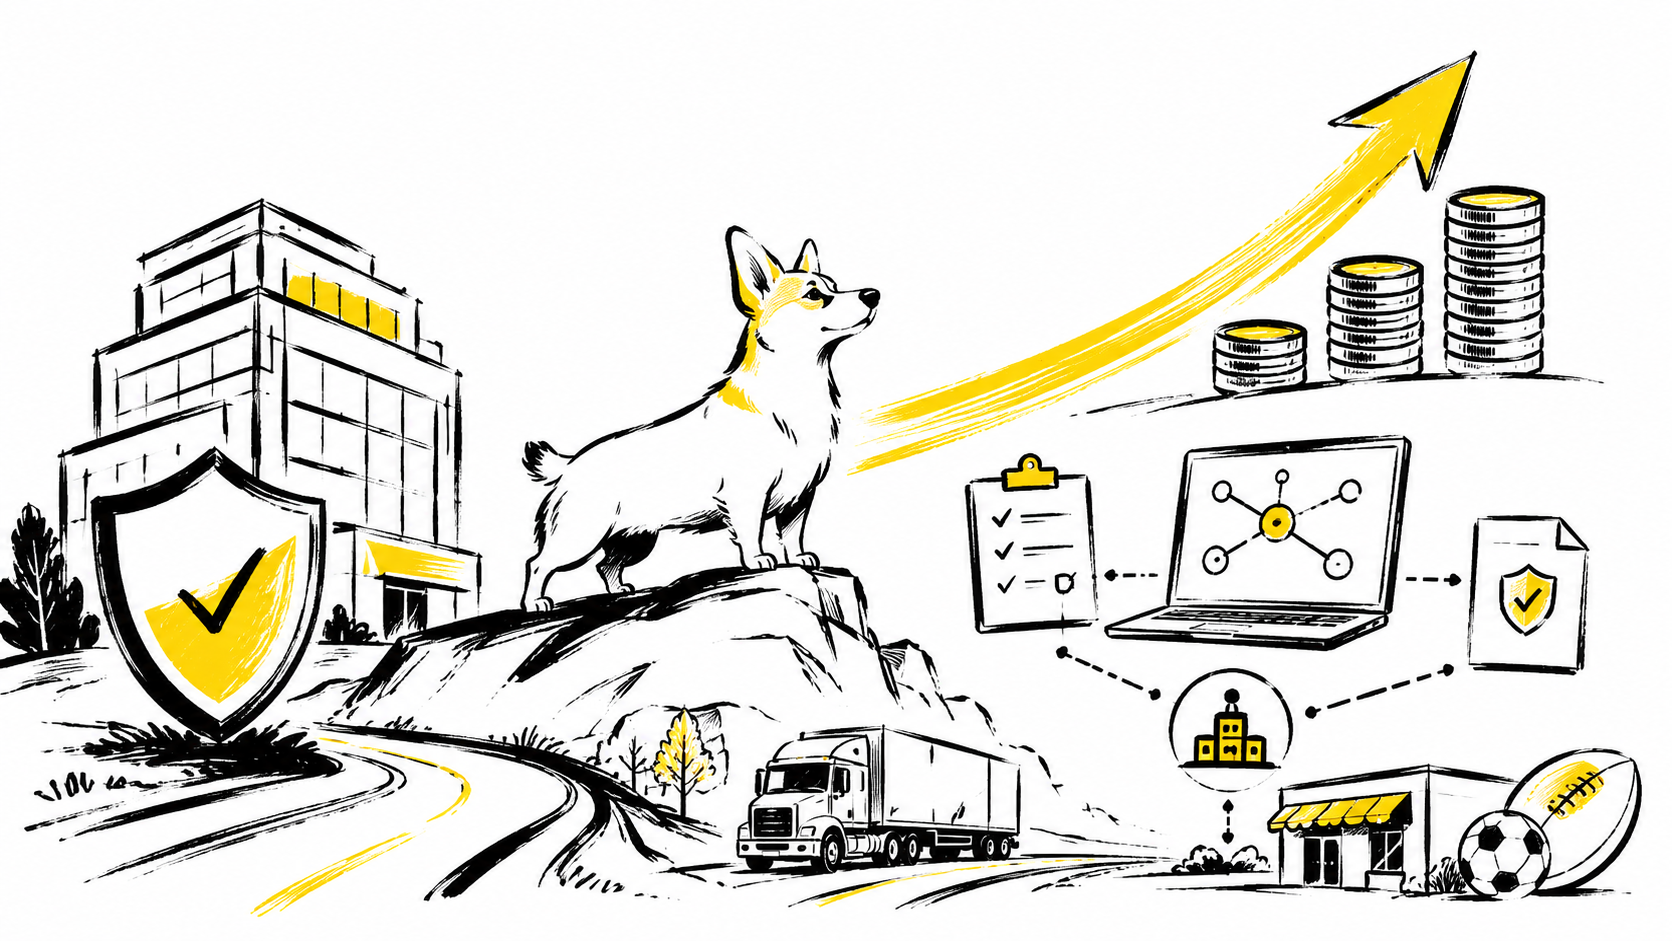
    Corgi is taking a full-stack approach, combining underwriting, claims handling and embedded insurance into a single platform designed for modern businesses.

    The company initially focused on startups, founder-led companies and other businesses underserved by traditional commercial insurance providers.

    Now, the new funding gives Corgi room to expand into additional verticals, including trucking, small business and sports.

    That expansion could be more significant than the funding headline itself.

    If Corgi can replicate its model across multiple commercial insurance categories, it is positioning itself not simply as an insurance provider, but as infrastructure for how commercial coverage is bought, underwritten and managed.


    The Bigger Fintech Signal

    Corgi’s rapid valuation increase highlights a broader shift happening across financial services.

    Investors are increasingly looking beyond consumer fintech apps and toward companies rebuilding the infrastructure underneath financial products.

    Insurance is a particularly large opportunity because so much of its underlying workflow still depends on systems and processes designed for a very different era.

    Corgi is betting that modern distribution, technology-driven underwriting and integrated claims infrastructure can turn that complexity into a scalable platform.

    The speed of its latest financing suggests investors are willing to pay aggressively for companies that can prove they are solving that infrastructure problem.


    Key takeaways for fintech startups

    • Infrastructure can command major valuations: Investors are increasingly backing the technology underneath financial services, not just the customer-facing product.

    • Speed matters: Corgi went from a $1.3B to $2.6B valuation in just three weeks, showing how quickly investor conviction can compound when growth is strong.

    • Vertical expansion creates leverage: Building infrastructure that can move across insurance categories can turn a niche product into a much larger platform.

    • Profitability changes the funding story: Raising large rounds while already profitable gives a company significantly more control over how it deploys capital.

    For fintech founders, Corgi is a useful reminder: the biggest opportunity may not be disrupting the financial product itself, but rebuilding the infrastructure that makes it possible.

    If you’re building a fintech infrastructure company and looking for help with growth strategy, positioning or go-to-market, Contact usâ ïżŒ.

  • Fasset Raises $68M at $1B Valuation to Build the Infrastructure for Borderless Banking

    Fasset Raises $68M at $1B Valuation to Build the Infrastructure for Borderless Banking

    Fasset has raised $68 million in Series C funding at a $1 billion valuation, making the stablecoin-focused fintech one of the latest companies to enter the global fintech unicorn club.

    The round was led by SBI Group, with participation from existing investor Speedinvest. It follows Fasset’s $51 million Series B in May, bringing its total funding raised in 2026 to $119 million.


    From stablecoin platform to financial infrastructure

    Founded in 2019, Fasset is building a financial platform that lets individuals, businesses and institutions receive, hold, move, spend and invest across currencies, markets and asset classes.

    Underneath it sits Own Network, Fasset’s regulated financial infrastructure connecting banks, payment providers, liquidity providers, custody partners and settlement networks across more than 100 banking corridors.

    The company says it now processes more than $40 billion in annualized transaction volume, serving 3 million+ wallets and more than 1,000 enterprises across 125 countries.


    Why SBI’s investment matters

    The most interesting part of this raise isn’t just the $1 billion valuation.

    It’s who led it.

    SBI Group is one of Japan’s major financial groups, spanning banking, securities, asset management, private equity and digital assets. Its investments include companies such as Ripple, Circle and Morpho.

    For Fasset, the relationship potentially provides access to something that can be more valuable than capital: an established financial ecosystem across Asia and international markets.

    SBI has already partnered with Fasset through SBI Remit, which provides access to a network supporting bank-account remittances to approximately 200 countries.

    The investment therefore fits directly into Fasset’s ambition to build cross-border financial infrastructure rather than simply another fintech application.


    Stablecoins become the infrastructure

    Fasset is increasingly positioning stablecoins as something that sits underneath the financial experience rather than something customers necessarily need to interact with directly.

    Parts of Own Network use stablecoins for settlement between markets where appropriate, while customers interact with financial accounts and products.

    The company is also applying AI to determine how transactions should move across payment rails, currencies, liquidity providers and settlement methods based on factors such as cost, speed and availability.

    The Series C will accelerate this work, particularly across stablecoin settlement, corridor banking and tokenized assets.


    The bigger bet: any-to-any banking

    Fasset’s long-term thesis is what CEO Mohammad Raafi Hossain describes as “any-to-any banking”: any person to any person, any asset to any asset and any rail to any rail.

    That is a much bigger proposition than building another stablecoin wallet.

    The company is betting that financial access should become increasingly independent of geography, with regulated local infrastructure connected to global assets and settlement networks through a single platform.

    Whether that becomes the next layer of global banking remains to be seen. But with $40 billion in annualized volume, 125 countries and now a $1 billion valuation, Fasset is no longer making that bet from the sidelines.


    Key takeaways for fintech startups

    • Strategic capital can matter more than capital alone. SBI gives Fasset access to a major financial ecosystem alongside its investment.

    • Infrastructure is becoming the bigger stablecoin opportunity. The value may increasingly sit in settlement and connectivity rather than consumer-facing wallets.

    • AI is moving deeper into fintech infrastructure. Fasset is using it to optimize routing across rails, currencies and liquidity providers.

    • Cross-border complexity creates opportunities. Connecting fragmented local financial systems remains one of fintech’s biggest infrastructure challenges.

    Fasset’s latest raise shows where stablecoin fintech may be heading next: away from being a new financial product and toward becoming invisible infrastructure for moving money globally.

    If you’re building in fintech and want to explore where opportunities like this could fit into your strategy, Contact us⁠.

  • Neno Raises €6.6M to Build AI-Native Financial Services for Europe’s SMEs

    Neno Raises €6.6M to Build AI-Native Financial Services for Europe’s SMEs

    Dutch fintech Neno has raised €6.6 million in seed funding to build an AI-native financial services platform for small and medium-sized businesses across Europe. The round was led by AlleyCorp, with participation from Motive Partners, Firstminute Capital, and angel investors from companies including Juni, Mollie, Deel, PayPal, Miro, Coinbase, and Hugging Face.

    The company is targeting a European accounting, tax, and professional services market that it estimates is worth more than €200 billion, while focusing on SMEs that remain dependent on fragmented financial software and traditional accounting services.


    Rebuilding the SME Finance Stack

    Neno combines banking, cards, bill payments, bookkeeping, tax, and payroll into a single financial workspace built around what it calls an agentic general ledger.

    The system brings transactional data into one place and uses AI to automate tasks such as reconciliation and tax categorisation, with Neno’s accountants reviewing the output before it is finalised.

    According to the company, its technology has made reconciliation and VAT preparation five times faster for its accountants, while customers save an average of eight hours of administration each month and 20% on annualised accounting fees.


    From AI Assistants to Ambient Finance

    Neno is also using the funding to develop what it calls Ambient AI, a step beyond AI systems that simply respond to instructions.

    The concept is for the system to continuously monitor a company’s finances and act within predefined limits, surfacing decisions to humans only when judgment is required. That could mean updating cash-flow forecasts when a major invoice arrives or paying routine bills automatically within agreed thresholds.


    Scaling the Accountant

    Neno says the goal is not to replace accountants, but to increase their capacity. Its model aims to allow a single accountant to manage hundreds of customers rather than the roughly 30-client capacity it associates with traditional accounting models.

    Since launching in Q1, the company says revenue has been growing 60% month-on-month, with more than 70% of new business coming through referrals.


    Key takeaways for fintech startups

    Neno’s funding highlights how AI could reshape financial services beyond traditional software automation. Key lessons include:

    • AI-native financial products can combine software with professional services.

    • Automation becomes more valuable when it increases human capacity rather than simply removing tasks.

    • Owning the underlying financial data can create a stronger foundation for AI-powered services.

    As European SMEs continue to navigate fragmented financial systems, Neno is betting that AI can turn accounting from a retrospective service into an always-on financial layer. Contact us to explore how Your Fintech Story can support your fintech strategy and growth.

  • Pouchers Raises $500K, With the Hardest Part Still Ahead

    Pouchers Raises $500K, With the Hardest Part Still Ahead

    Pouchers has raised $500,000 in pre-seed funding and officially exited beta, marking an important step for the fintech as it prepares to build beyond its early product. But while the funding makes for the headline, the company’s own account of the journey points to a less visible challenge: turning an early-stage product into something users can consistently trust.

    The road to the raise involved late-night engineering sessions, product testing, customer conversations, and constant iteration as the team worked through problems that do not appear in a funding announcement.


    Building Is Only Half the Job

    Getting the product ready is one challenge. Getting people to understand it, use it, and keep coming back is another.

    Pouchers is now focusing on areas including onboarding, activation, product adoption, and user communication. As the product evolves, the team also has to make sure new features are understandable to new users while existing customers can make the most of them.

    That creates a continuous feedback loop between the people building the product and the people using it.


    When Everyone Owns the Problem

    Pouchers also highlights how responsibilities can quickly overlap inside an early-stage fintech. Engineering issues can become customer experience problems, support can uncover product weaknesses, and growth teams can identify friction that requires changes elsewhere.

    The company describes this shared ownership as an important part of how it operates. When something affects customers, the question is often less about whose responsibility it is and more about getting it resolved.


    Key takeaways for fintech startups

    Pouchers’ milestone offers a reminder that early fintech growth is about more than securing capital. Key lessons include:

    • Exiting beta is the start of a new phase of product development.

    • Customer support can provide critical insight into product weaknesses.

    • Early teams often need to work across traditional functional boundaries.

    • Trust becomes especially important when a fintech handles customers’ money.

    The $500,000 gives Pouchers more room to build, but the bigger challenge is turning that early momentum into a product that can scale. Contact us to explore how Your Fintech Story can support your fintech strategy and growth.